R&D tax claims used to be reasonably forgiving. You could do the work through the year and sort out the detail at claim time, building the narrative, working out roughly which costs counted and apportioning them afterwards, and HMRC would usually accept it.
However, that's no longer true, and software companies are among the most exposed to the new system. The test of a genuine technological advance is subjective and routine development is easy to over-claim, so software claims draw particular scrutiny.
HMRC now expects claims to rest on contemporaneous, apportioned evidence built while the work happens. It enforces that through the mandatory Additional Information Form, its Guidelines for Compliance, and a sustained rise in enquiries, now running at around one in five claims.
For the finance team, the practical effect is that claims now stand or fall on data captured while the work was happening. Staff-time and technical details carry the most weight. But the expense side, which is the part that's often left until last, is something you can lock down straight away. In this article we'll explain how.
What HMRC expects now
Now that HMRC has shifted from narrative to record, it's no longer enough to describe what was R&D and roughly what it cost at year end. You need to show evidence created at the time. That means costs identified as R&D-linked when they were incurred, and apportioned to projects as the year went on rather than reverse-engineered afterwards.
Under its new approach, HMRC tends to discount polished write-ups produced after the fact, because there's no hard evidence they reflect what actually happened.
Why year-end reconstruction fails
Reconstructing a claim at year-end means going back through twelve months of spend, trying to recall which costs belonged to which project and in what proportion.
HMRC now requires evidence that each cost was captured at the time it was incurred, and a figure worked out months later can't show that. If the evidence wasn't built as the spend happened, there's usually no honest way to build it afterwards, and inspectors who sense reconstruction have an easy line of challenge.
So how do you capture evidence that holds up?
Now it’s essential to build the evidence as you spend, rather than as you claim. On the expense side, that means rethinking how you tag spend. You need to link R&D-related purchases and relevant details to the right project as they happen, so the records already exist in the right shape at claim time.
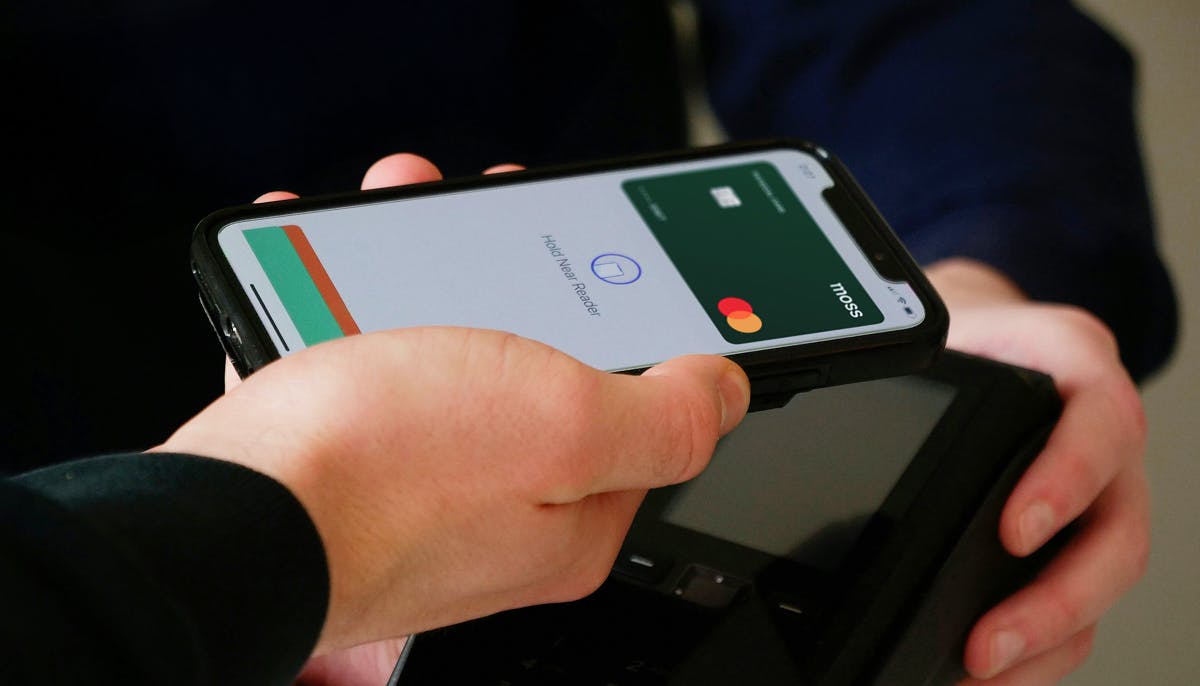
Moss Expense Management and Reimbursements help finance teams enforce mandatory fields and project or cost-centre tagging at the point of spend, so the expense side of your R&D claim is captured correctly and timestamped as you go.
The upside of getting this right is money you keep. Without a tagging workflow that captures R&D spend as it happens, qualifying costs get stripped out of a claim, or drag the whole claim into an enquiry, simply because you can’t evidence them to the standard HMRC now expects. That is relief you were entitled to, lost to a record-keeping gap rather than to the rules themselves.
What Moss can't evidence for you
Expenses are only one part of a claim and not the part HMRC weighs hardest. The evidence HMRC weighs most heavily sits outside spend data altogether: the staff-time records showing who spent how long on qualifying work, the sprint logs behind them, and the technical narrative arguing the work sought a genuine advance. Each needs its own time-tracking and documentation, kept up through the year and no more reconstructable at claim time than your costs are.
So treat clean expense data for what it is: one solid, finished part of the claim, not the whole of it. It closes the expense gap well, but a claim under scrutiny is only as strong as its weakest section, and staff-time and technical evidence are the sections HMRC leans on hardest.
If R&D claims are part of your year, check now, rather than at claim time, whether your expense records would stand up as contemporaneous evidence. Read the guide to R&D-ready expense records.