If you run finance in a UK agency that has just merged or is about to, it's tempting to keep both finance setups running for now and sort it out once the dust settles. It sounds sensible, but for most small agency combinations it stretches a job that should take a quarter into one that runs past a year. It all comes down to the fact that you need a set date to work towards, and a small merger rarely comes with one.
In this article we'll look at why big holding-company mergers tend to move faster than small agency mergers, which decisions in your own merger can be made early, and how to run one spend process over two sets of books while the bigger questions get argued out.
The merger with a deadline
One famous example of a big fast moving merger is that of Omnicom and Interpublic. Omnicom completed its acquisition of Interpublic on 26 November 2025, and by February it had doubled its cost-synergy target to $1.5bn, with $900m of that expected in 2026 (Omnicom Q4 2025 results, 18 February 2026). A merger of this size moves quickly on systems because the synergy number is public, it is reported against every quarter, and there is an entire integration team whose job is to hit it.
The merger without one
Most agency deals in the UK look nothing like Omnicom. Moore Kingston Smith counted 301 deals across UK media and marketing services in 2025, down 23% on the year before, and most marketing-services deals were acquisitions of traditional, service-led agencies. A Unit4 survey of professional services firms found that 86% of finance and IT leaders say integrations take longer than planned, with one in five running past a year.
So, say you're the financial controller of a 45-person creative agency that has just combined with a 30-person performance marketing shop, and you're both on Xero. The smaller one already runs its spend through Moss, while yours puts production costs on a company Amex.
That now gives you two supplier lists, potentially with a dozen of the same freelancers on both, two sets of approval habits, and a ledger question that keeps getting parked because the two managing directors haven't agreed which Xero file survives.
Two decisions that got stuck together
There are two key decisions at play, the first being ledger and entity structure. That includes which Xero file survives, whether the two companies stay as separate entities or one trade moves into the other, and how the combined accounts get prepared. Ultimately that decision lies with the owners and the accountants. It takes months because it touches tax, ownership and client paperwork at the same time.
The second decision is the operating process, including who can approve what, whose cards people use, which supplier list is the real one, and when the payment run happens. That belongs to you as the financial controller, and it's independent of the first decision, because each legal entity can keep feeding its own ledger whatever process sits on top of it.
Waiting for the ledger decision and then doing everything at once means the operating mess compounds for as long as the partners argue. On the other hand, copying the bigger agency's approvals policy onto the smaller one by email and spreadsheet gets you the rule without the mechanism.
What can you unify before the ledger question is settled?
The answer is actually more than you might assume. In the first quarter after completion, without touching either set of books, you can set a date for:
1. One approval policy, by amount and team, applied the same way on both sides
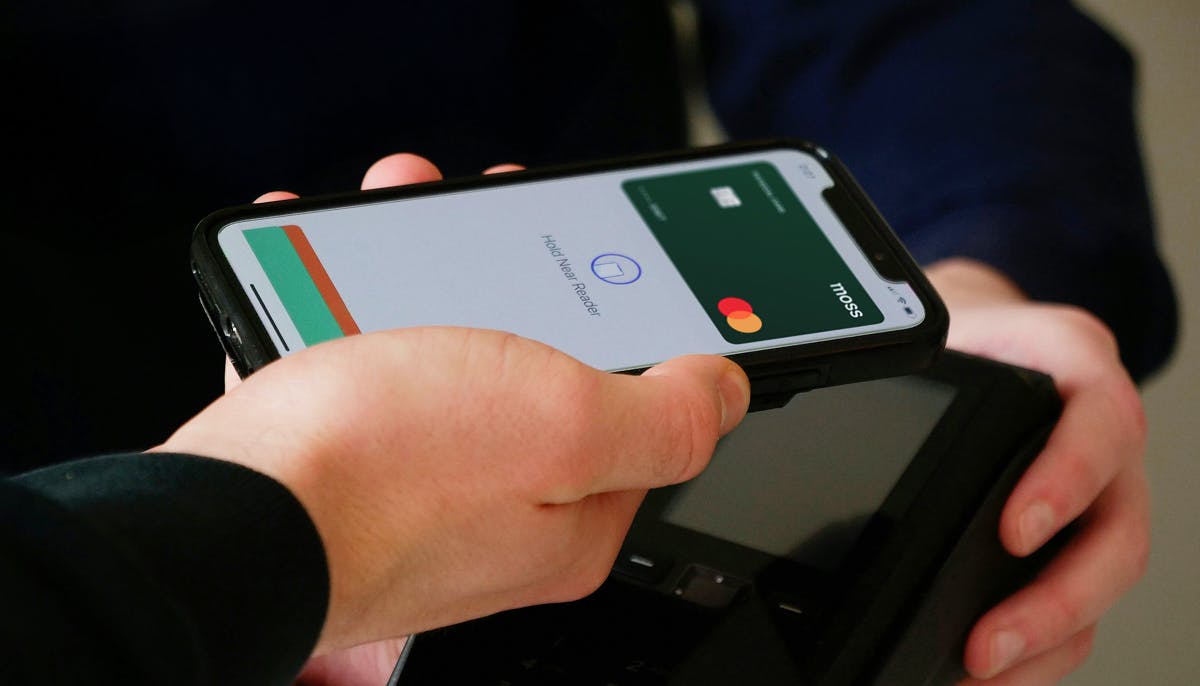
2. One card programme, with limits per card, replacing the Amex and the personal-card expensing
3. One supplier master, with the freelancer overlap de-duplicated so the same editor isn't paid twice under two names
4. A weekly payment run for each entity, from the same place, with two people signing off
Each legal entity keeps its own books and its own accounting connection. The process on top is shared, and that is what stops the duplicate payments, the unapproved production spend and the two-column management accounts long before anyone has settled which entity survives.
Running one process over two sets of books
With Moss you run the combined business as one organisation, with each legal entity as its own entity connected to its own ledger. Each entity has its own approval rule book, so the shared policy is set up identically in both, with routing by amount, team, supplier or cost centre; cards carry per-card limits; and approved invoices are paid from each entity's own wallet with two people authorising.
Moss gives you one process and a view of spend across both entities. The ledgers themselves, and the group accounts, stay where they always were; consolidation and intercompany balances are the accountant's job. If both agencies already use Moss, one account becomes the organisation and the other is set up as an entity inside it, so in the situation above you would decide in week one that the performance shop's account is the organisation and yours the second entity. Moss is built for combinations of this size; a holding-company group with several treasuries and dozens of entities needs a different tool.
You can find out more about multi-entity setup in Moss here.